
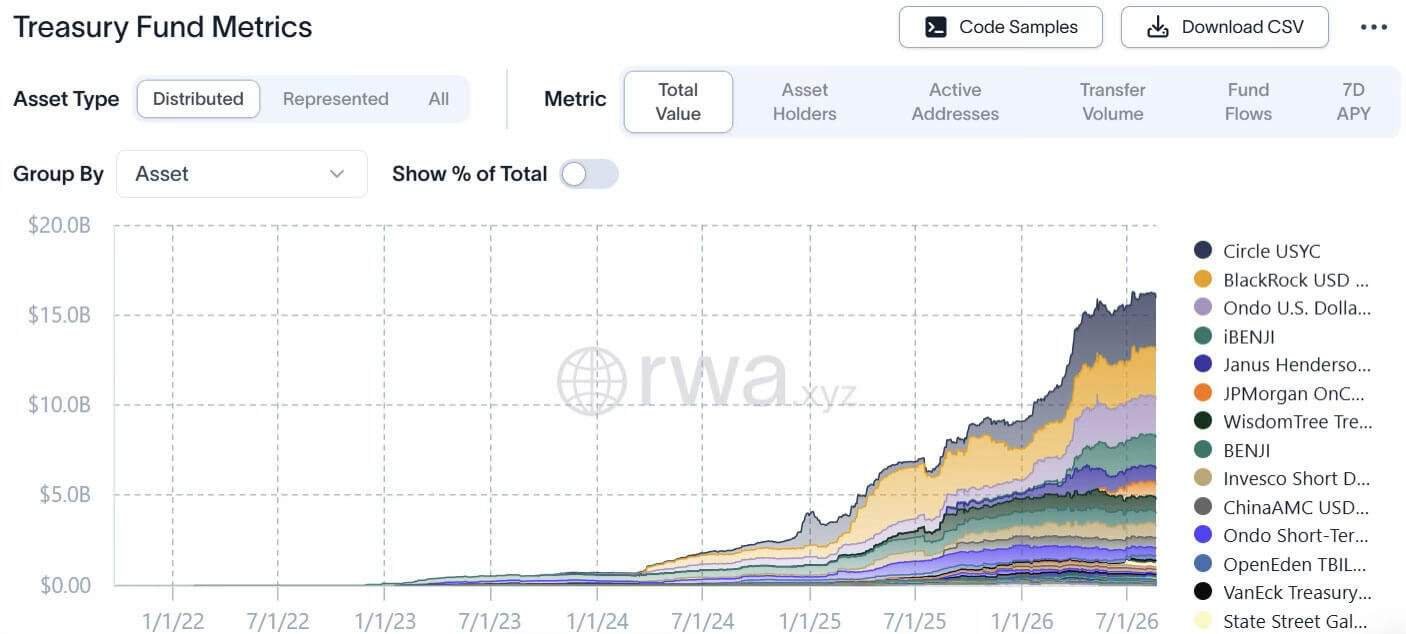
Roughly $16 billion sits in tokenized US Treasury funds today. Most of it does nothing.
It gets held. It gets transferred now and then. Eventually somebody redeems it. That’s the whole lifecycle for the typical tokenized fund, and it’s why the industry’s favorite metric, total value issued onchain, has quietly stopped being useful.
Issuance is a solved problem at this point. The issuer list already includes most of the biggest names in traditional asset management. The harder question, and the one almost nobody puts on a slide, is what an asset is actually allowed to do once it exists onchain.
Redeeming versus borrowing looks the same on paper and isn’t
Take an investor sitting on a tokenized fund that owns $100 million of bonds. Cash is needed. The conventional route is to redeem, wait for the underlying assets to settle, collect the proceeds and redeploy.
The plumbing runs faster than it would offchain. The economics don’t change at all. The investor gave up the position to get the liquidity.
Now run the same need through a lending market. Deposit the token as collateral, borrow stablecoins against it, keep the credit exposure and its yield, sell nothing. Same balance sheet entry, completely different outcome.
Vincent Maliepaard, vice president of marketing at Sentora, frames that gap as the line between tokenization as a faster distribution channel and tokenization as financial infrastructure. Traditional markets already run an enormous amount of machinery whose only job is mobilizing the value locked inside assets rather than owning them. That machinery is what’s now up for grabs as programmable code.
DeFi liquidates in minutes and credit settles in days
Here’s where the pitch meets reality. A lending protocol can’t treat every tokenized asset as interchangeable.
When ETH breaks through a liquidation threshold, the protocol dumps it into a market that never closes and whose depth anyone can read onchain. A tokenized credit portfolio behaves nothing like that. The underlying bonds trade during traditional market hours. NAV may be struck periodically instead of continuously. Redemption can take days.
Wrapping the thing in a token doesn’t close that gap. Closing it takes design work around the token, not inside it. Which means an asset built for distribution and an asset built for collateral use deserve very different standards, and right now plenty of issuers are shipping the first while marketing the second.
What mWIN gets right, and who’s grading it
mWIN, launched in August 2026, is worth looking at because it was built against the collateral question from day one rather than retrofitted.
Midas issues the token. Wellington Management runs the underlying credit strategy. Northern Trust holds the assets. The strategy was issued natively onchain instead of wrapped around an existing fund after the fact, and the portfolio spans investment-grade CLOs and other asset-backed credit at a current yield of around 6.9%.
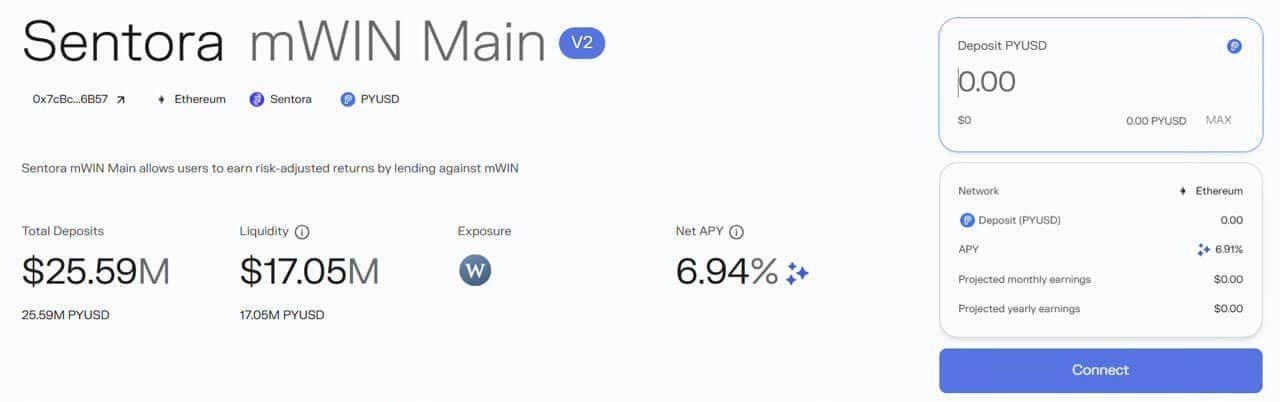
The mechanics matter more than the yield. mWIN can be minted and redeemed daily on a T+1 basis, pulling from several competing liquidity sources rather than depending on secondary market depth to bail it out.
Sentora then curates a Morpho market where mWIN backs loans in PayPal’s PYUSD, setting parameters from a dossier of historical NAV, past market stress events, liquidity and redemption mechanics. The point of all that homework is a loan-to-value limit sized so a forced sale can finish before the collateral is worth less than the debt.
Worth flagging: Maliepaard works for the firm curating that market, so treat the case study as an argument from an interested party. The underlying design principle stands on its own. The token makes the asset programmable, and the arrangements bolted around it are what make the programmability safe to touch.
Better numbers than total value issued
Counting assets issued onchain lumps idle tokens in with working ones, which is why the figure keeps going up while the utility question stays open.
The more revealing questions are already measurable. How much tokenized collateral is securing loans. How much stablecoin liquidity can be raised against tokenized securities. How much collateral moves between venues without selling the underlying asset, and how much of that settles without leaving the common infrastructure.
Early signs point that way. Figure PRIME’s growth on Morpho this year surpassed 200 million. Aave launched Horizon in August 2025 specifically so institutions could borrow stablecoins against tokenized assets, and it’s currently carrying a TVL of over $250 million.
More Morpho markets keep getting built around tokenized credit, and tokenized equities are arriving on the same rails.
Digitizing documents didn’t make the internet matter. Networking them did. Financial assets look to be walking the same road, from representation to distribution and now to utility, and the scoreboard that eventually counts is what markets can build with these assets rather than how many of them exist. If you’re evaluating a tokenized fund next quarter, skip the AUM number and ask what a lending market will lend against it.