
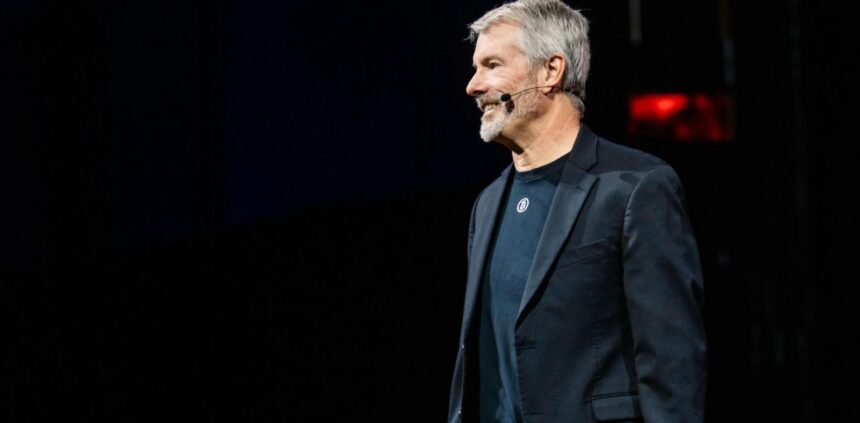
The crypto industry spent years lobbying for the Clarity Act. This week the Senate killed it, 49 votes for and 50 against. And Michael Saylor, the man whose company holds more bitcoin than almost anyone, says that’s fine.
Writing on X on Saturday, the Strategy founder and chair argued that legislation can lock in restrictions just as easily as it locks in rights. The blockage, in his telling, is good for the digital asset space.
It’s a contrarian read. Lawmakers on Tuesday mostly voted against advancing a bill that would formally divide oversight between regulators, spelling out which digital assets count as securities, commodities or stablecoins. That’s the kind of clarity companies have been begging for since the Biden Administration hit them with fines for allegedly selling unregistered securities.
Saylor’s case: regulators are already moving
His argument rests on what the watchdogs are doing without Congress. The Securities and Exchange Commission has offered conditional relief for onchain trading of certain tokenized stocks. The Commodity Futures Trading Commission Chairman has stated a willingness to act without the bill.
Saylor, whose company Strategy started buying bitcoin in 2020, contends that rulemaking of this sort gives crypto companies the regulation they need. No statute required.
“We have an administration willing to modernize financial markets. We should use the next two years to put better financial products into people’s hands,” Saylor wrote.
He continued: “Let the Digital Assets industry innovate rapidly in a free market and create the greatest possible value for the U.S. and global economy.”
The parts of the bill he didn’t want
There’s a second layer to his position. Saylor argued that some proposals inside the act wouldn’t have helped the crypto space anyway. He singled out limits on paying customers for holding payment stablecoins.
That’s a detail worth sitting with. The industry’s loudest voices treated the Clarity Act as a single yes-or-no question for years, but the text carried trade-offs, and Saylor is now framing its failure as dodging a bad deal rather than losing a good one.
How it fell apart
President Donald Trump urged lawmakers last month to pass the bill, and the push helped spur a bitcoin rally. But Republicans warned for months that Democrats were deliberately holding it back, and Tuesday’s 49-50 vote confirmed the stall.
Despite the hurdle, the SEC and CFTC are pushing ahead with rulemaking on their own. Whether that agency-by-agency approach survives a change in administration is the question Saylor’s optimism skips past, and it’s the one that makes a statute worth having in the first place.
For now, the bitcoin treasury pioneer is betting that two years of a friendly White House beats a law he didn’t fully like.