
Aave’s DAO would eat the first 33 ETH of bad debt on Core WETH before a single volunteer underwriter loses anything. That’s the part of the Sept. 11 Umbrella proposal from TokenLogic worth reading twice, because it inverts the usual order of who bleeds when a liquidation goes wrong.
The proposal covers lenders supplying wrapped Ether (WETH), USDC or USDT to Aave V4’s Core liquidity Hub on Ethereum. Three markets. Not the whole protocol.
The numbers are targets, not money in the bank
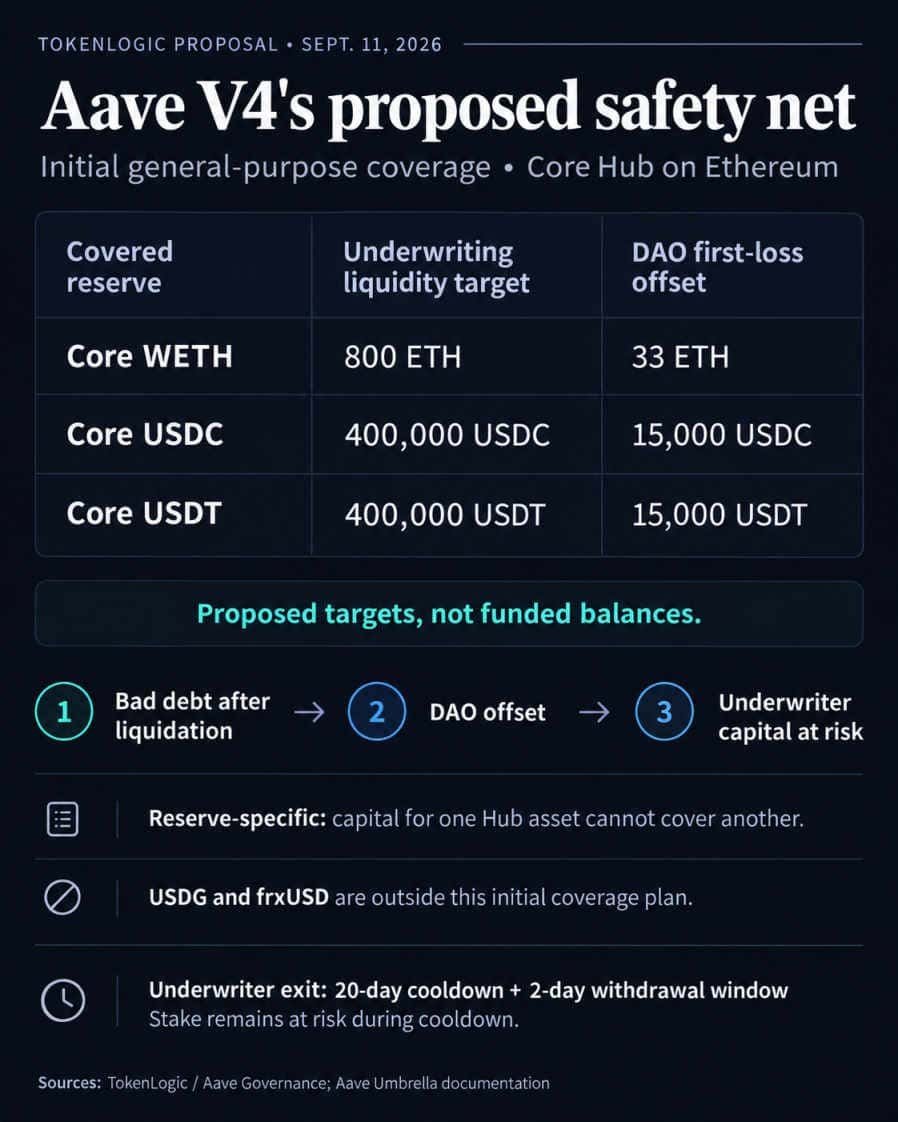
TokenLogic proposes underwriting targets of 800 ETH for Core WETH, 400,000 USDC for Core USDC and 400,000 USDT for Core USDT. Those figures were sized against six to eight weeks of expected loan growth.
Read that carefully. They’re targets for a proposed configuration. Nobody has committed that capital to protecting lenders yet, and the proposal doesn’t pretend otherwise.
The DAO’s first-loss layer is smaller and more concrete: 33 ETH for Core WETH, 15,000 USDC for Core USDC and 15,000 USDT for Core USDT, absorbed through what the proposal calls “deficit offsets.”
Your coverage stops at the reserve, and that trips people up
Here’s the detail most suppliers will get wrong. Coverage attaches to the specific reserve receiving your deposit, not to the token.
Supply USDC to Core USDC and you’re covered. Supply the same USDC to a different Hub and you’re not. Capital allocated to one Hub asset can’t clear another reserve’s deficit, full stop.
Bad debt shows up when a liquidation burns through a borrower’s collateral and leaves debt unpaid. Past the DAO’s offset layer, Umbrella underwriters can lose their committed capital covering that gap. The mechanism is a burn of supplied Hub shares.
Until it’s used, that capital keeps earning supply yield, and additional rewards compensate participants for taking the loss risk. Reasonable trade. But it is a trade.
Spoke loans still land on the Core reserve
Eligibility extends to all borrowing from each protected reserve, including loans originated through Spokes, the components where debt is created. Those loans can have collateral sitting in entirely different Hubs.
Doesn’t matter. The credit line still exposes the Core reserve that supplied the borrowed asset, so the backstop has to answer for it.
The exit is slower than the pitch suggests
Each proposed market sets a 20-day cooldown followed by a two-day withdrawal window. Miss the window and Aave’s withdrawal guidance says you activate another cooldown and wait a further 20 days.
And starting the exit doesn’t get you out of harm’s way. Aave’s Umbrella documentation says staked assets remain exposed to slashing during cooldown while continuing to earn rewards.
So the extra yield comes bundled with both potential capital loss and restricted access to your own funds. Anyone treating underwriting as a slightly spicier savings account should sit with that for a minute.
What TokenLogic left out, and why
No initial general-purpose coverage for USDG or frxUSD. TokenLogic cites uncertainty over incentive-sensitive lending activity and whether the market can attract underwriters who genuinely transfer risk away from existing suppliers. For frxUSD, it flags a concentrated, issuer-linked supplier base.
Other Hubs’ reserves sit outside the initial plan too, for reasons including limited incremental protection and narrow supplier bases.
Worth stating plainly: exclusion isn’t an accusation. It doesn’t mean those loans lack collateral or that losses are coming.
TokenLogic proposes monitoring conditions after activation and reassessing the framework after three months, with excluded markets reconsidered as lending activity matures and supplier bases diversify.
If you’re supplying to Core WETH, USDC or USDT today, the number to watch isn’t the 800 ETH headline target. It’s whether underwriters actually show up to fill it, because the 33 ETH offset is the only layer the DAO has actually put its name to.