
Tether just walked into private credit at the exact moment the people already in it are having a bad quarter.
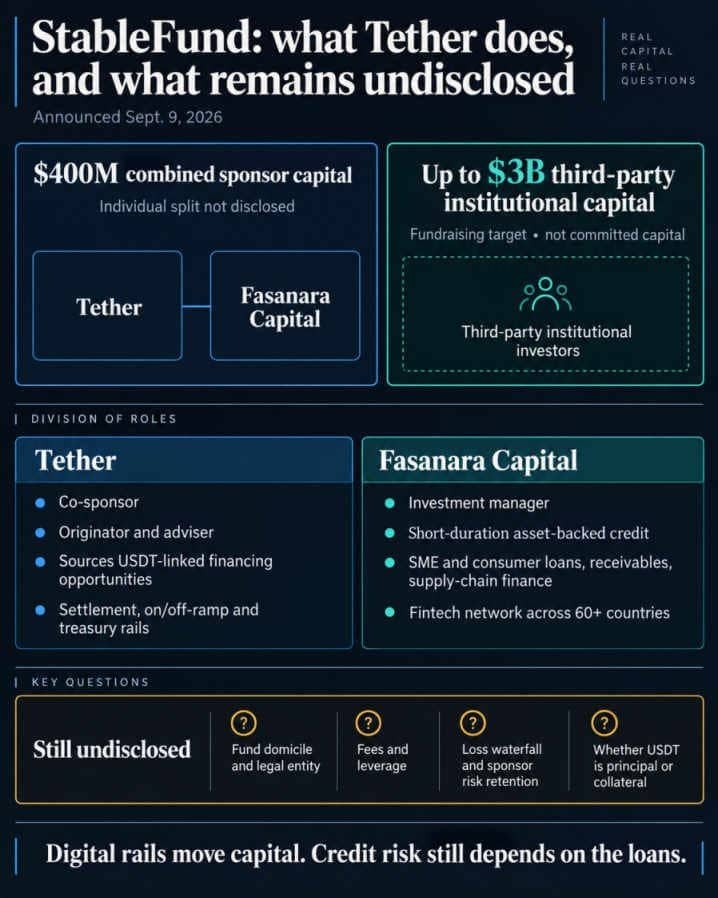
On Sept. 9, the stablecoin issuer and London-based Fasanara Capital launched StableFund with $400 million in combined sponsor capital and plans to raise up to $3 billion more from institutional investors. Fasanara manages the portfolio. Tether helps originate USDT-linked financing opportunities and provides settlement and treasury infrastructure.
The industry they’re entering is worth roughly $3 trillion. It’s also showing cracks.
The defaults are the story
An August Wall Street Journal analysis found worsening loan health and investor returns across publicly traded funds overseen by Ares Management, Blackstone, Blue Owl Capital and Golub Capital. Defaults at those vehicles reached their highest levels since at least 2021. Blue Owl’s default rate rose to 2.8% in the second quarter, its highest in at least five years.
Large managers have pushed back on the idea that this signals a broader crisis, arguing portfolio credit quality remains resilient. They have a point on the raw numbers. Default rates remain below levels reached during more severe episodes such as the Covid-19 shock.
But the deterioration is arriving alongside redemption pressure from investors and concern about heavily indebted borrowers, including software companies facing possible disruption from artificial intelligence. That’s the backdrop against which Tether wants billions of dollars from institutions that are, right now, paying closer attention to credit quality and liquidity than they were two years ago.
Tether already runs a lending book. This one is different
This isn’t Tether’s first credit operation. Galaxy Research estimates Tether controlled around 60% of the $23 billion centralized crypto-lending market at the end of June, giving it roughly $13.5 billion of outstanding secured loans.
StableFund is an attempt to take that machinery somewhere much larger: financing actual businesses and consumers rather than crypto counterparties. It’s a bigger asset class, with a different risk shape, at a time when regulators and investors are looking harder at private credit than they have in years.
What’s in the portfolio isn’t corporate direct lending
Worth being precise here, because the stress reports and the strategy aren’t describing the same thing.
Fasanara, which manages more than $6 billion, plans to deploy the fund into short-duration, asset-backed loans across a fintech network spanning more than 60 countries. The portfolio will include financing for small and medium-sized businesses and consumers, plus trade receivables and supply-chain credit.
That’s a different animal from the corporate direct lending showing up in the Blue Owl and Golub numbers. Short duration and asset-backed means faster turnover and something to seize when a borrower stops paying.
The regulator already wrote the warning
In May, the Financial Stability Board warned that private credit has yet to be tested through a prolonged economic downturn. It flagged weaker borrower quality, high leverage, opaque valuations and growing links between private funds, banks and insurers as potential vulnerabilities. It pointed to the rising use of payment-in-kind arrangements and rising defaults as evidence of borrower stress.
The FSB also singled out the growth of funds offering redemption options, saying liquidity pressures could amplify stress when investors seek their money back.
StableFund is structured as an evergreen vehicle, so it can keep raising and deploying capital rather than winding down at a set maturity. Tether and Fasanara have not publicly detailed its redemption terms. For a fund launching into the FSB’s specific concern, that’s a gap you’d want filled.
Tether sits near the front of the pipeline
What separates this from a conventional Fasanara vehicle is where Tether sits. The USDT issuer acts as co-sponsor, originator and adviser, sourcing opportunities linked to its stablecoin network while supplying on- and off-ramp connectivity and treasury rails.
So Tether isn’t just providing a token that borrowers and lenders settle in. It has a hand in deciding where capital gets pointed.
Fasanara remains the investment manager and is responsible for deploying the portfolio. The announcement doesn’t say Tether will make final underwriting decisions. It doesn’t establish that USDT will serve as loan principal, collateral, or the fund’s denomination either.
The number they didn’t break down
Here’s the thing nobody disclosed, and it’s the thing that matters most.
The companies described the $400 million anchor as a joint commitment but didn’t split it between the sponsors. They also didn’t disclose fund leverage, fees, or whether either sponsor’s capital absorbs losses before money raised from third-party institutions does.
Those terms get more consequential every quarter defaults keep climbing across private markets. A large junior commitment from Tether would create a completely different risk profile than a smaller investment sitting alongside outside institutions on equal terms.
Until someone puts a number on Tether’s share of that $400 million and says where it sits in the loss stack, treat the operational role and the financial exposure as two separate questions. Only one of them has been answered.