
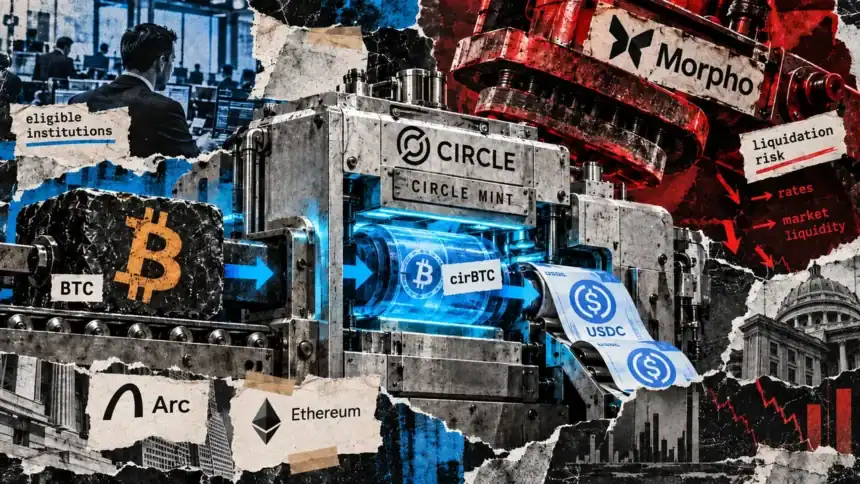
Circle has cut the number of screens a treasury desk clicks through to turn Bitcoin into dollars. It hasn’t cut the risk. That still sits inside a Morpho lending market, and Circle isn’t pretending otherwise.
Since Sept. 21, eligible Circle Mint institutions can deposit native BTC, mint cirBTC, post that token as collateral and receive USDC, all in one coordinated workflow. The service is live on Arc and Ethereum.
The pitch is fewer systems for raising dollar liquidity without selling Bitcoin. The fine print is that Circle runs the front door and a third party sets the terms behind it.
What Circle runs and what it doesn’t
Under what Circle calls its Digital Asset-Backed Borrowing service, the customer deposits native BTC, mints cirBTC and supplies it as collateral through a customer-controlled wallet. The borrowed USDC then settles into the customer’s Circle Mint balance.
Circle Mint is the account interface. cirBTC is Circle’s tokenized claim backed by native Bitcoin. Morpho supplies the lending market, and that’s where the decisions that matter get made.
Borrowing costs, collateral limits, liquidation thresholds, available liquidity and availability all come from the selected market, not from Circle. Morpho’s documentation describes each market as its own combination of loan asset, collateral, oracle, interest-rate model and liquidation loan-to-value limit.
That distinction has teeth. A position can become liquidatable even though the underlying Bitcoin was never sold, because the cirBTC sits in the lending market. A tidier interface doesn’t relieve a treasury team of watching collateral values, utilization and borrowing costs.
The launch-day numbers on Arc
A Sept. 21 snapshot of the Arc market for USDC loans against cirBTC showed an 86% liquidation loan-to-value limit. The market held $14.13 million borrowed against $162.85 million in available liquidity, for a $176.99 million market size and 7.98% utilization.
At least one borrow appeared in the activity log that day. So the market was operating, not just listed.
Treat those figures as a point-in-time reading. They describe Arc only and don’t apply to the Ethereum market.
How much cirBTC is out there
Circle’s reserve dashboard reported 948.75081803 cirBTC outstanding against 951.25857454 BTC in reserves as of Sept. 20. About 397 cirBTC sat on Arc and about 552 on Ethereum.
Arc, Circle’s own layer-1 network, runs on a permissioned validator set. For an institution choosing between the supported networks, that’s another line item to weigh alongside the market terms.
Access is narrow. The service is limited to eligible institutions, excludes New York clients and is subject to jurisdiction and eligibility checks.

Shorter path, same credit
The launch shortens the trip from held Bitcoin to USDC. It doesn’t turn variable DeFi credit into a fixed Circle loan, and nothing in the workflow changes who gets liquidated when the collateral slips.
Whether the service produces lasting cirBTC demand will depend on continued borrowing activity and the market terms that hold after the launch-day snapshot.
Bitcoin is up 4.75% over the past 24 hours and sits at rank No. 1 by market cap. If you’re running a treasury and read the Circle name as a promise of fixed terms, open the Morpho market page first. The 86% line belongs to it, and so does the liquidation.